

On 17 September 2026, the African Peer Review Mechanism (APRM), in conjunction with Development Reimagined, hosted the second webinar, “What Actually Drives an African Sovereign Rating: Understanding the Methodologies, Confronting Negative Overlays, Methodological Penalties, and the African Risk Premium,” as part of the series on African credit rating agencies, bringing together academic researchers, economists, rating experts, and policymakers to unpack how sovereign ratings are constructed and applied in practice.
The session explored the mechanics of rating methodologies, the realities of the African Risk Premium, and how the upcoming launch and operationalisation of the African Credit Rating Agency (AfCRA) fits into the broader financial architecture.
Ms. Ejigayhu Tefera, Senior Economist and Researcher on Credit Ratings at APRM, kicked off the session with an opening speech that set the stage for the timely and important discussion, emphasising that ratings form part of the infrastructure of global finance and that AfCRA’s value lies in providing an additional independent source of credit opinion rather than replacing existing agencies or guaranteeing higher ratings.
Dr. Daniel Cash, Fellow (Non-Resident) at the United Nations University Centre for Policy Research (UNU-CPR), followed with a presentation on the structure of sovereign ratings, highlighting that credit ratings evaluate creditworthiness rather than price, and urging governments to build stronger internal evaluative capabilities to engage more effectively with external assessors.
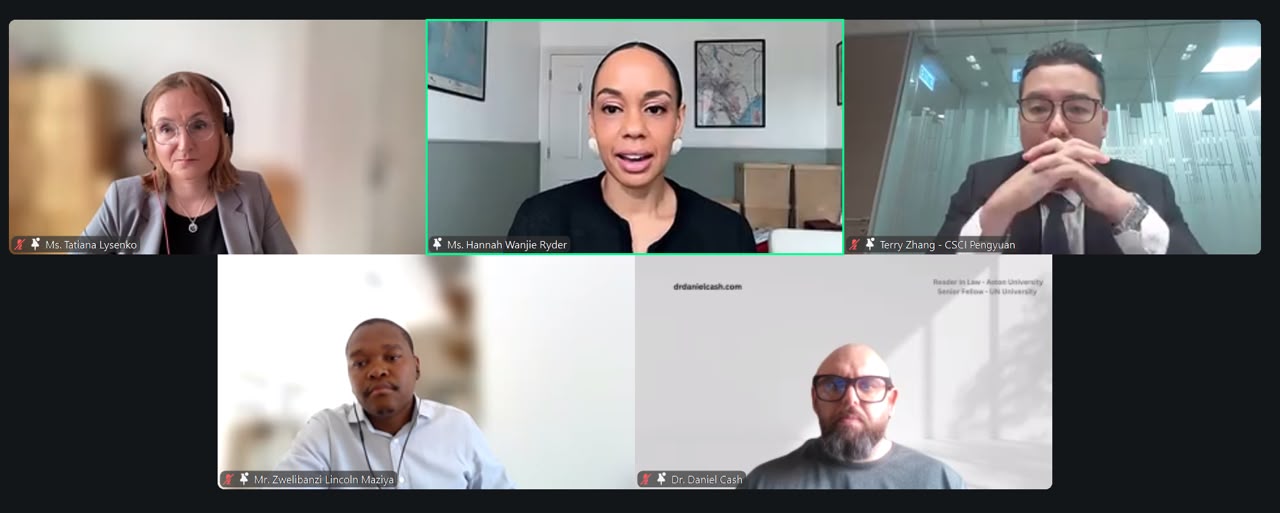
The event then moved into a panel discussion, moderated by Ms. Hannah Ryder, CEO of Development Reimagined. Panellists included Ms. Tatiana Lysenko, Research Fellow, Finance for Development Lab and former Lead Economist at S&P Global Ratings, Mr. Zwelibanzi Lincoln Maziya, Chief Ratings Officer, Sovereign Africa Ratings, and Mr. Terry Zhang, Head of Global Strategy and Business Management at CSCI Pengyuan International (CSPI Ratings).
Here are five takeaways from the panel discussion include:
- Emphasis on the need for credit rating agencies to distinguish default risk from market pricing, and the presiding influence of committee discretion. Daniel Cash highlighted that a credit rating is an opinion on creditworthiness rather than a direct price tag for borrowing. Dr Cash highlighted that final interest rates are driven by investment banks, market demand, and overall market structure, and noted that published methodologies only provide a structure and that committee deliberations and qualitative overlays play a decisive role.
- Debt-servicing and liquidity capacity reflect default risk far better than traditional debt-to-GDP ratios. Tatiana Lysenko noted that standard debt-to-GDP metrics often overlook the economic realities of developing countries and that focusing on metrics such as interest-to-revenue ratios, debt-servicing capacity, foreign currency debt exposure, and external liquidity provides a much clearer picture of repayment capacity.
- Incorporating local realities requires evaluating active economic usage, rather than static underground wealth. Zwelibanzi Lincoln Maziya, explained how Sovereign Africa Ratings factors natural resources into its methodology by assessing active extraction levels and local beneficiation rather than simply placing a value on unmined underground reserves.
- Sovereign credit assessments inherently reflect subjective worldviews and qualitative judgement. Terry Zhang pointed out that rating frameworks are structured around specific worldviews and must be calibrated to a country’s distinct stage of development to avoid penalising structural economic transitions.
- Need for African sovereigns to build internal evaluative capabilities in preparation for the launch and operationalisation of AfCRA. Ejigayhu Tefera highlighted that AfCRA is designed to provide independent, context-aware evaluations rather than guarantee higher ratings, and in addition, to engage effectively, African governments need dedicated credit liaison teams and greater data transparency to present their evidence base directly to rating committees. Panellists agreed on AfCRA’s value-add as an independent African voice within the rating ecosystem, adding that initial focus should be around ensuring clear processes are put in place.

